
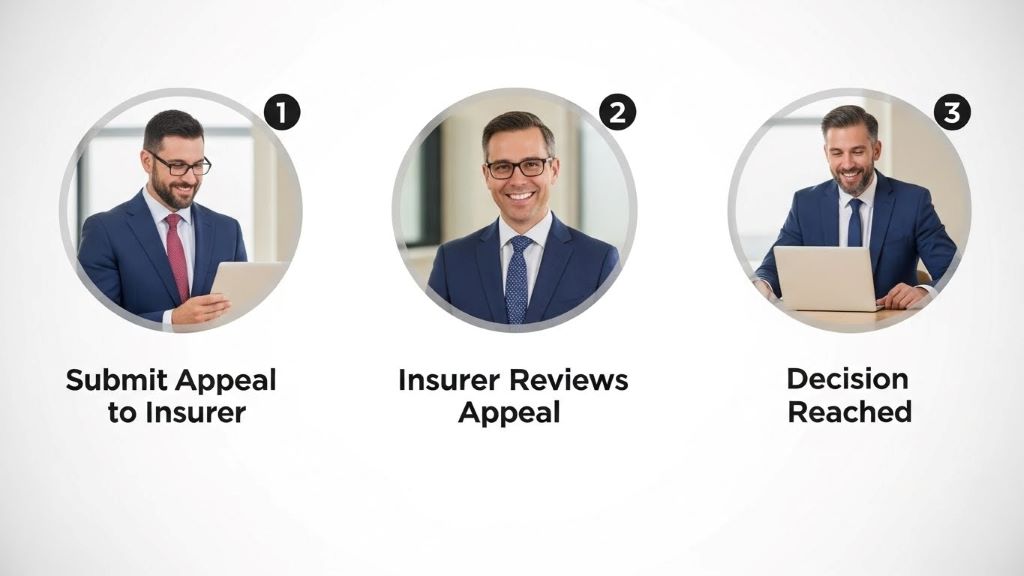
When your insurance claim gets rejected, it can feel overwhelming and frustrating. Many policyholders across the United Kingdom face this challenge every year. Understanding your rights and options is essential. If you’re dealing with a denied claim, seeking guidance from professionals like Lawyer Car Injury can make a significant difference in your appeal process.
Insurance companies sometimes deny claims for various reasons. These reasons may include incomplete documentation, policy exclusions, or disputes about liability. However, a denial doesn’t mean the end of your case. You have several appeal options available. Knowing how to navigate these options can help you secure the compensation you deserve.
Understanding Why Insurance Claims Get Denied
Insurance claim denials happen more often than most people realize. Companies may reject your claim due to missing information or late submissions. Sometimes, they argue that the damage isn’t covered under your policy terms. Other times, they dispute the extent of your injuries or the accident circumstances.
If was straco’s insurance claim denied in uk state, understanding the specific reason becomes your first priority. The insurer must provide a clear explanation in writing. This explanation should detail why they rejected your claim and which policy terms they’re citing.
Common reasons for denial include:
- Policy exclusions that weren’t properly explained
- Lack of sufficient evidence or documentation
- Missed deadlines for filing claims
- Disputes about who caused the accident
- Pre-existing conditions that insurers claim aren’t covered
- Allegations of fraud or misrepresentation
Additionally, insurers sometimes deny claims based on technicalities. They might argue that you didn’t notify them quickly enough. Alternatively, they could claim you failed to cooperate with their investigation. These reasons often feel unfair to policyholders who believe they followed proper procedures.
Your Right to Appeal an Insurance Denial
The good news is that you can challenge an insurance denial. The Financial Conduct Authority (FCA) regulates insurance companies in the UK. They require insurers to have formal complaints procedures. Therefore, you have legal protections when disputing a denied claim.
Your first step involves reviewing the denial letter carefully. Look for specific policy clauses mentioned and the reasoning provided. Check your policy document to verify whether their interpretation seems accurate. Sometimes, insurers misapply policy terms or overlook important details.
Next, gather all relevant documentation. This includes accident reports, medical records, photographs, and witness statements. Strong evidence can overturn an initial denial. Moreover, having organized documentation shows the insurer you’re serious about your appeal.
The Internal Appeals Process
Most insurance companies require an internal review before external intervention. This process typically involves submitting a formal complaint to the insurer’s complaints department. You should do this in writing, clearly explaining why you believe the denial was incorrect.
When writing your appeal letter, be specific and factual. Reference policy terms that support your position. Include any new evidence that wasn’t part of your original claim. Furthermore, set a reasonable deadline for their response, typically 8 weeks as per FCA guidelines.
The insurer must acknowledge your complaint within five business days. They should provide a final response within eight weeks. However, if your case is complex, they may request additional time. During this period, maintain detailed records of all communications.
Escalating to the Financial Ombudsman Service
If the internal appeal doesn’t resolve your issue, you can escalate to the Financial Ombudsman Service (FOS). This free, independent service investigates disputes between consumers and financial companies. According to the Financial Ombudsman Service, they handle thousands of insurance complaints annually.
You must wait until you receive a final response from your insurer or until eight weeks have passed since your complaint. The FOS will review your case impartially. They consider both your evidence and the insurer’s position. Their decisions are binding on the insurance company if you accept them.
The FOS process typically takes several months. Nevertheless, many consumers find satisfaction through this route. The service doesn’t charge fees, making it accessible to everyone. Their ombudsmen have extensive experience with insurance disputes and understand policy complexities.
Legal Action and Court Proceedings
Sometimes, the dispute amount exceeds what the FOS can handle, or you prefer legal action. You can take your insurance company to court. Small claims court works for disputes up to £10,000. For larger amounts, you’ll need county court proceedings.
Legal action requires careful consideration. Court proceedings involve costs, even if you win. However, if your claim is substantial and you have strong evidence, litigation might be worthwhile. Solicitors specializing in insurance disputes can advise whether court action makes sense.
Before proceeding, consider alternative dispute resolution methods. Mediation can resolve conflicts faster and cheaper than court battles. Many insurers prefer settling disputes through mediation rather than facing lengthy court proceedings.
Gathering Evidence to Support Your Appeal
Strong evidence significantly increases your appeal success rate. Start by collecting comprehensive documentation about your accident and damages. Medical reports should detail your injuries, treatment, and prognosis. Repair estimates should come from reputable garages or professionals.
Witness statements add credibility to your version of events. If anyone saw the accident, ask them to provide written statements. Photographs of damage, injuries, and accident scenes prove invaluable. Meanwhile, police reports offer independent verification of accident circumstances.
Expert opinions sometimes become necessary. Engineers can assess vehicle damage, while medical experts can confirm injury severity. Although expert reports cost money, they often prove decisive in complex cases. Therefore, consider them an investment in your claim’s success.
Working with Professional Representatives
Navigating insurance appeals can be complicated. Professional help often improves outcomes significantly. Solicitors specializing in insurance claims understand policy language and legal precedents. They know how to present evidence effectively and counter insurer arguments.
Claims management companies also assist with appeals. However, research carefully before engaging them. Some charge high fees or make unrealistic promises. The Citizens Advice Bureau provides free guidance on choosing reputable representatives and understanding your options.
Many solicitors offer no-win-no-fee arrangements for insurance disputes. This arrangement means you only pay if your appeal succeeds. Consequently, legal help becomes more accessible to people regardless of financial circumstances.
Understanding Policy Terms and Exclusions
Policy documents contain crucial information about coverage limits and exclusions. Reading these documents carefully helps you understand whether the denial has merit. Insurers sometimes deny claims based on exclusions that policyholders didn’t realize existed.
Common exclusions include:
- Driving under the influence of alcohol or drugs
- Using your vehicle for business without proper coverage
- Modifications not disclosed to the insurer
- Deliberate damage or illegal activities
- Wear and tear or gradual deterioration
However, insurers must explain exclusions clearly when selling policies. If they failed to highlight important exclusions, you might have grounds for appeal. Consumer protection laws require transparent policy terms that average customers can understand.
Time Limits and Deadlines
Insurance appeals involve strict timeframes. Missing deadlines can jeopardize your case permanently. Most policies require claim notification within specific periods after an accident. Additionally, appeal procedures have their own deadlines that you must respect.
Generally, you should submit internal appeals promptly after receiving denial letters. The FOS requires complaints within six months of the insurer’s final response. Court proceedings also have limitation periods, typically three years for personal injury claims.
Therefore, act quickly when your claim gets denied. Delays weaken your position and may eliminate appeal options entirely. Setting reminders for important deadlines helps ensure you don’t miss crucial opportunities.
What to Expect During the Appeal Process
Appeals require patience and persistence. The process typically takes several months from start to finish. During this time, the insurer may request additional information or clarification. Respond promptly to all requests to avoid unnecessary delays.
Insurers sometimes make settlement offers during appeals. Evaluate these offers carefully against your claim’s full value. Don’t feel pressured to accept inadequate settlements. However, be realistic about your case’s strengths and weaknesses when considering offers.
Throughout the process, maintain professional communication with the insurer. Emotional or aggressive language rarely helps. Instead, focus on facts, evidence, and policy terms. Clear, respectful communication often produces better results than confrontational approaches.
Preventing Future Claim Denials
Learning from denied claims helps prevent future problems. Always notify your insurer immediately after accidents. Provide complete, accurate information in all communications. Keep detailed records of everything related to your claim.
Review your policy annually to understand coverage and exclusions. Ask questions if anything seems unclear. Moreover, disclose all relevant information when purchasing or renewing policies. Non-disclosure can invalidate claims later.
Consider whether your current coverage adequately protects you. Sometimes, paying slightly higher premiums for comprehensive coverage prevents disputes. Additionally, maintaining good relationships with your insurer through prompt premium payments and honest communications can facilitate smoother claims processes.
Conclusion
Having your Straco insurance claim denied doesn’t mean losing hope. Multiple appeal options exist to challenge unfair denials. Start with the internal appeals process, then escalate to the Financial Ombudsman Service if necessary. Strong evidence, clear communication, and persistence often overturn initial denials.
Understanding your policy terms and rights as a consumer empowers you throughout the appeal process. Professional guidance from solicitors or claims specialists can significantly improve your chances of success. Remember that insurers must treat customers fairly and provide valid reasons for denials.
Take action promptly when facing a denial. Gather comprehensive evidence, follow proper procedures, and don’t accept unfair decisions without challenge. Your policy represents a contract, and insurers must honor their obligations. With determination and the right approach, many denied claims ultimately succeed on appeal.
Frequently Asked Questions
How long do I have to appeal an insurance claim denial?
You typically have no strict legal deadline for internal appeals, but acting within weeks is advisable. For the Financial Ombudsman Service, you must complain within six months of receiving the insurer’s final response. Court proceedings generally must begin within three years for personal injury claims.
Can I appeal a denial if I missed the original claim deadline?
Yes, you can explain why you missed the deadline in your appeal. Valid reasons include medical emergencies, lack of awareness about the deadline, or insurer delays in providing information. However, success depends on the circumstances and the insurer’s discretion.
Do I need a solicitor to appeal my insurance claim denial?
No, you can handle appeals yourself. The internal complaints process and Financial Ombudsman Service are designed for consumers without legal representation. However, solicitors can be helpful for complex cases or when significant amounts are involved.
What happens if the Financial Ombudsman sides with the insurance company?
If you disagree with the FOS decision, you can still pursue legal action through the courts. The ombudsman’s decision only becomes binding if you accept it. However, their decisions carry significant weight and often indicate how courts might view your case.
Will appealing affect my insurance premiums or future coverage?
No, making a legitimate appeal shouldn’t impact your premiums or coverage. Insurers cannot penalize you for exercising your right to challenge decisions. However, any successful claim may affect your no-claims bonus according to your policy terms.
Related Topics:
Dallas Car Injury Claims – Trusted Agency Info